1Treaties in a nutshell
2Which country may tax what?
| Usually taxed by | Dutch relief | |
|---|---|---|
| Real estate abroad | The country where it is | Exemption |
| Foreign bank accounts | The Netherlands (residence country) | Credit for any foreign tax withheld |
| Foreign shares and funds | The Netherlands | Credit for dividend tax withheld abroad |
| Salary for work done abroad | Often the country where you work | Exemption, with progression |
| Foreign pension | Depends on the treaty and type of pension | Varies |
3Exemption or credit
- Exemption method (vrijstellingsmethode)
- The part of the Dutch Box 3 tax that belongs to the foreign assets is removed entirely.
- Credit method (verrekeningsmethode)
- The foreign assets stay in the Dutch tax base, but Dutch tax is reduced by the foreign tax paid, at most the Dutch tax on those assets.
- 1Total Box 3 taxon all assets
- 2Foreign sharenotional yield abroad ÷ total yield
- 3Reliefthat share of the tax
- 4Tax duewhat is left
4Worked example: an apartment abroad
- Savings in the Netherlands
- €100,000
- Apartment abroad
- €200,000
- Box 3 tax before relief
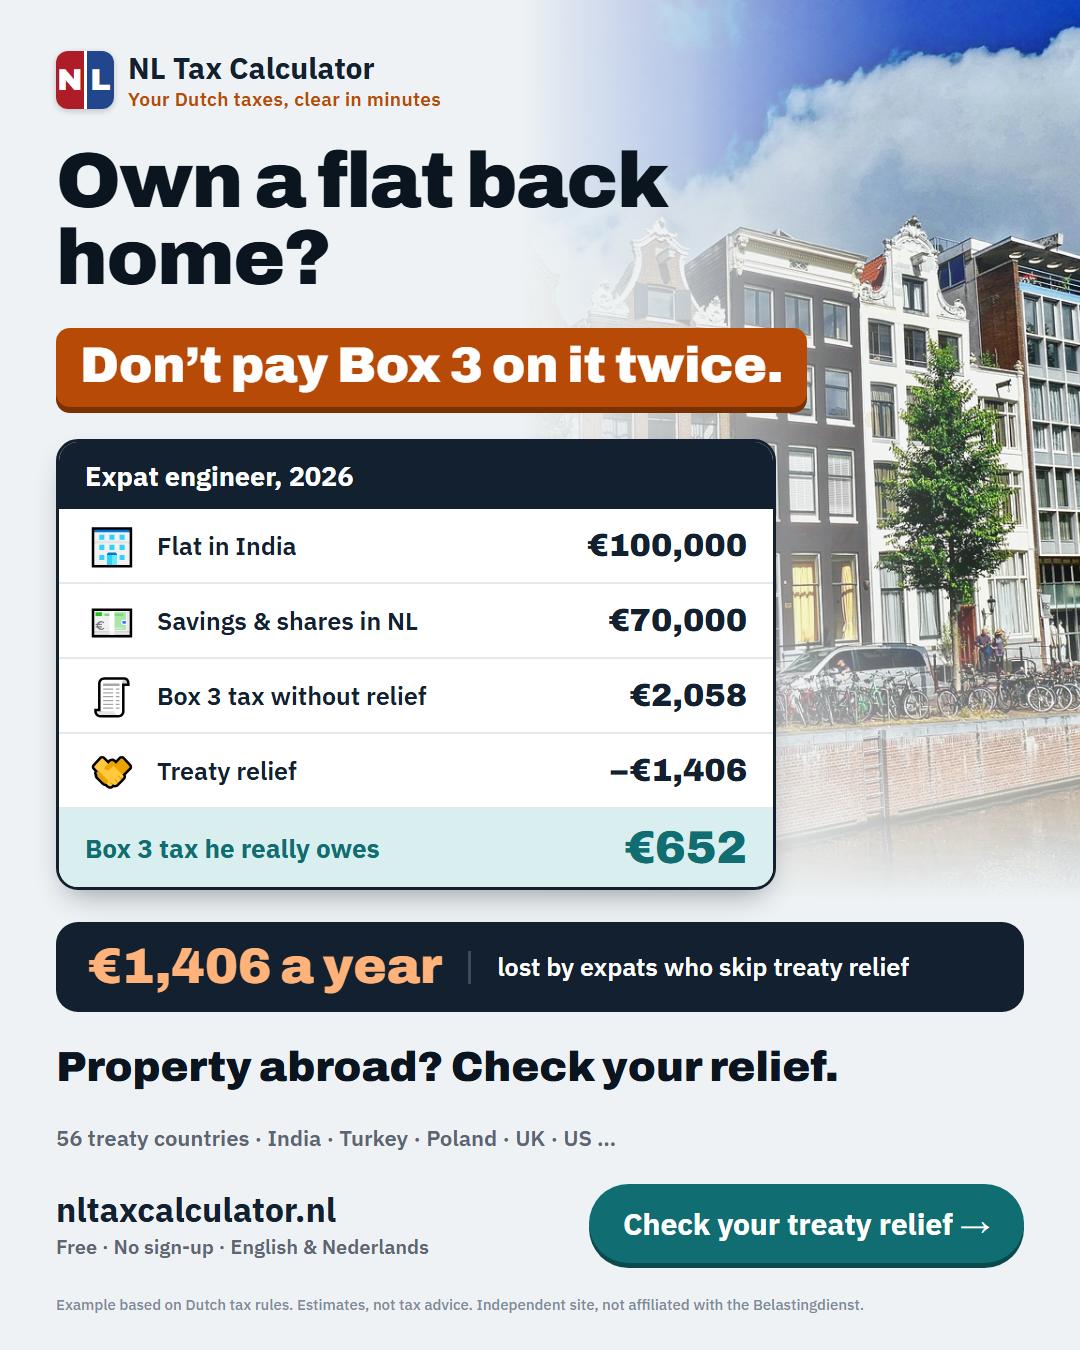
- €3,835
- Relief for the apartment (exemption)
- − €3,465
- Box 3 tax after relief
- €370
5The countries the calculator covers
- All 56 listed countries
- Real estate: exemption. Bank accounts, shares and other investments: credit for tax withheld abroad.
- Which countries
- Argentina, Australia, Austria, Belgium, Bosnia and Herzegovina, Brazil, Bulgaria, Canada, China, Croatia, Czech Republic, Denmark, Egypt, Ethiopia, Finland, France, Germany, Ghana, Greece, Hong Kong, Hungary, India, Indonesia, Ireland, Israel, Italy, Japan, Latvia, Lithuania, Mexico, Morocco, New Zealand, Nigeria, North Macedonia, Norway, Pakistan, Philippines, Poland, Portugal, Romania, Serbia, Slovakia, South Africa, South Korea, Spain, Sri Lanka, Sweden, Switzerland, Thailand, Tunisia, Turkey, Ukraine, United Kingdom, United States, Venezuela and Vietnam: each has a treaty in force and at least 5,000 residents in the Netherlands.
- Any other country
- Choose "Other": real estate is still exempt under the Dutch unilateral decree (Bvdb 2001).
6Special cases
The same Dutch relief applies, but the US also taxes its citizens on worldwide income wherever they live. See the US-Dutch double tax calculator.
The unilateral decree (Besluit voorkoming dubbele belasting 2001) gives exemption for real estate and credit for other income, much like a treaty.
The rent is taxed where the home is; in the Netherlands the home stays in Box 3 with exemption.
7Documentation you need
8Common questions
Do I declare a foreign property I do not rent out?
Yes, at its value on 1 January; the relief then removes the Dutch tax on it.
Which exchange rate do I use?
The rate on the reference date (1 January) for Box 3, from a reliable source such as the ECB.
Is a foreign mortgage deductible?
In Box 3 it counts as a debt against your assets above the debt threshold; it is not deductible in Box 1.
What about my first year?
Sources
This article is based on these official pages. If anything here differs from them, the official page is right.
Ready to run your own numbers?
Full tax calculator with treaty relief