The three types
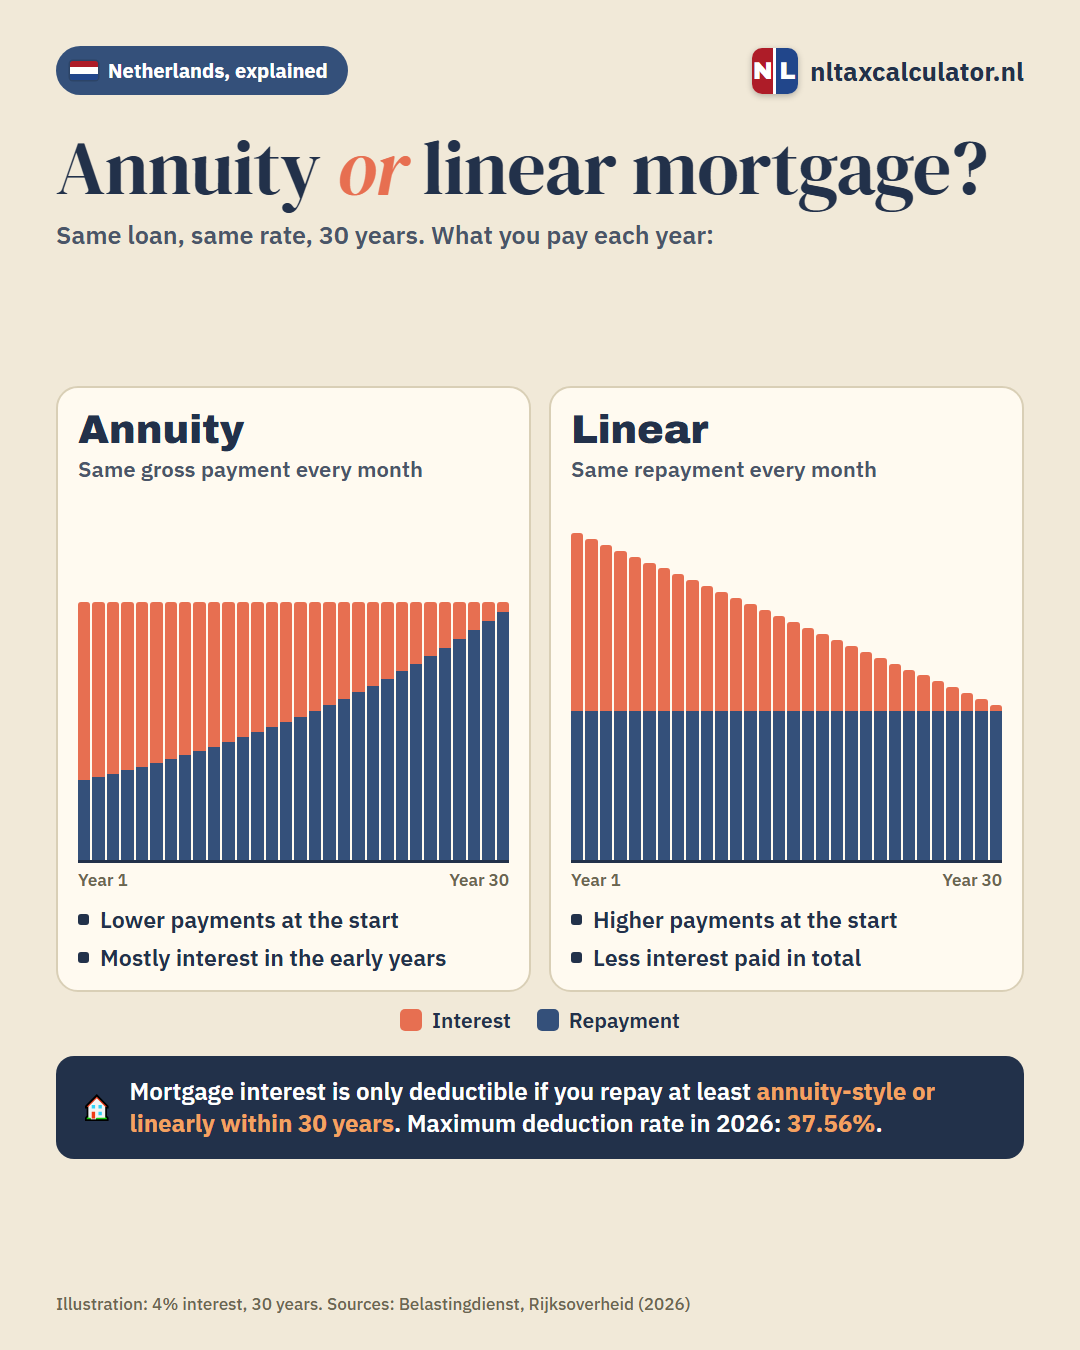
The same gross payment every month. At first it is mostly interest; the repayment part grows each month. The most common choice.
The same repayment every month plus interest on what is left. High payments at the start, falling steadily. Least interest in total.
Only interest, no repayment: the whole loan is still owed after 30 years. Interest is not deductible for new loans since 2013, and lenders allow it only for part of the loan.
Part of the series Buying a home in the Netherlands: every step and every mortgage topic, with worked examples.
€400,000 over 30 years, side by side
Average gross payment per month in each year, 3.8% interest for the whole term (an assumption: in reality the rate is reset after each fixed period)
| Annuity | Linear | Interest-only | |
|---|---|---|---|
| Year 1 | €1,864 | €2,358 | €1,267 |
| Year 5 | €1,864 | €2,190 | €1,267 |
| Year 10 | €1,864 | €1,978 | €1,267 |
| Year 15 | €1,864 | €1,767 | €1,267 |
| Year 20 | €1,864 | €1,556 | €1,267 |
| Year 25 | €1,864 | €1,345 | €1,267 |
| Year 30 | €1,864 | €1,134 | €1,267 |
| Total interest, 30 years | €270,979 | €228,633 | €456,000 |
| Still owed after 30 years | €0 | €0 | €400,000 |
Annuity: interest and repayment per month in selected years.
Linear: the same scale, so you can compare the bars.
The formulas
- Annuity payment
- M = L × r ÷ (1 − (1 + r)^−n), with L the loan, r the yearly rate ÷ 12, n the number of months (360).
- Linear payment in month k
- L ÷ n + r × (L − (k − 1) × L ÷ n). The first month here is €2,378, the last €1,115.
- Interest-only
- L × yearly rate ÷ 12 = €1,267 a month, for as long as the loan runs.
Net payments: the effect of the deduction
Interest is deductible, repayment is not. So early on, when an annuity is mostly interest, the net payment is much lower than the gross one, and the gap narrows over time. A linear mortgage has a higher net payment at the start but falls fastest. With the deduction capped at 37.56%, the net cost of €1,000 of interest is at least €624.
See the mortgage interest deduction for the net cost by income.
The 2013 rules
- Before 2013Old loans keep their rules
Interest-only and savings or investment mortgages taken out before 1 January 2013 keep their deduction (overgangsrecht), for at most 30 years from the start, and from 1 January 2001 for older loans.
- From 2013Annuity or linear, within 30 years
New loans for your own home are only deductible if you repay at least on an annuity or linear schedule within 30 years, as agreed in the contract.
- Raised laterA new part gets its own 30 years
Increase your mortgage and the new part must meet the 2013 rules, with its own 30-year clock.
Mixing types
- Many buyers split the loan into parts, for example an annuity part and a linear part, each with its own fixed period.
- Lenders usually allow an interest-only part up to about half the home's value. That part has no deduction, counts as a Box 3 debt, and is tested with stricter percentages.
- If you already have an old interest-only part from before 2013, you can usually take it with you when you move: keep it if the deduction matters to you.
General information for 2026, not financial advice. Lenders apply the rules in their own way, and rates change daily. Before you sign, have your own situation checked by a registered mortgage adviser.
How much can I borrow? · Annuity, linear or interest-only · Interest rates and fixed periods · Mortgage interest deduction · NHG · Buying costs · Mortgages for expats · Moving, repaying, divorce, selling · Mortgage glossary
Sources
This article is based on these official pages. If anything here differs from them, the official page is right.
Ready to run your own numbers?
Mortgage calculator